

I was counting data centers with my toddler over the weekend, as one does. She wanted to count the dots. I was counting megawatts. That is basically the whole Texas story.
Last week I made a map about two Texases. It showed how the first one was built around people and the second is now being built around compute. I still think that’s basically right. But it was missing something, and the thing it was missing is that compute itself is splitting.
If you count sites, existing or planned, the map still looks urban. Dallas. Houston. Austin. San Antonio. Cities pull compute toward them, so the footprint clusters right where you’d expect: near people, fiber, customers, labor, logistics. That map is not wrong.
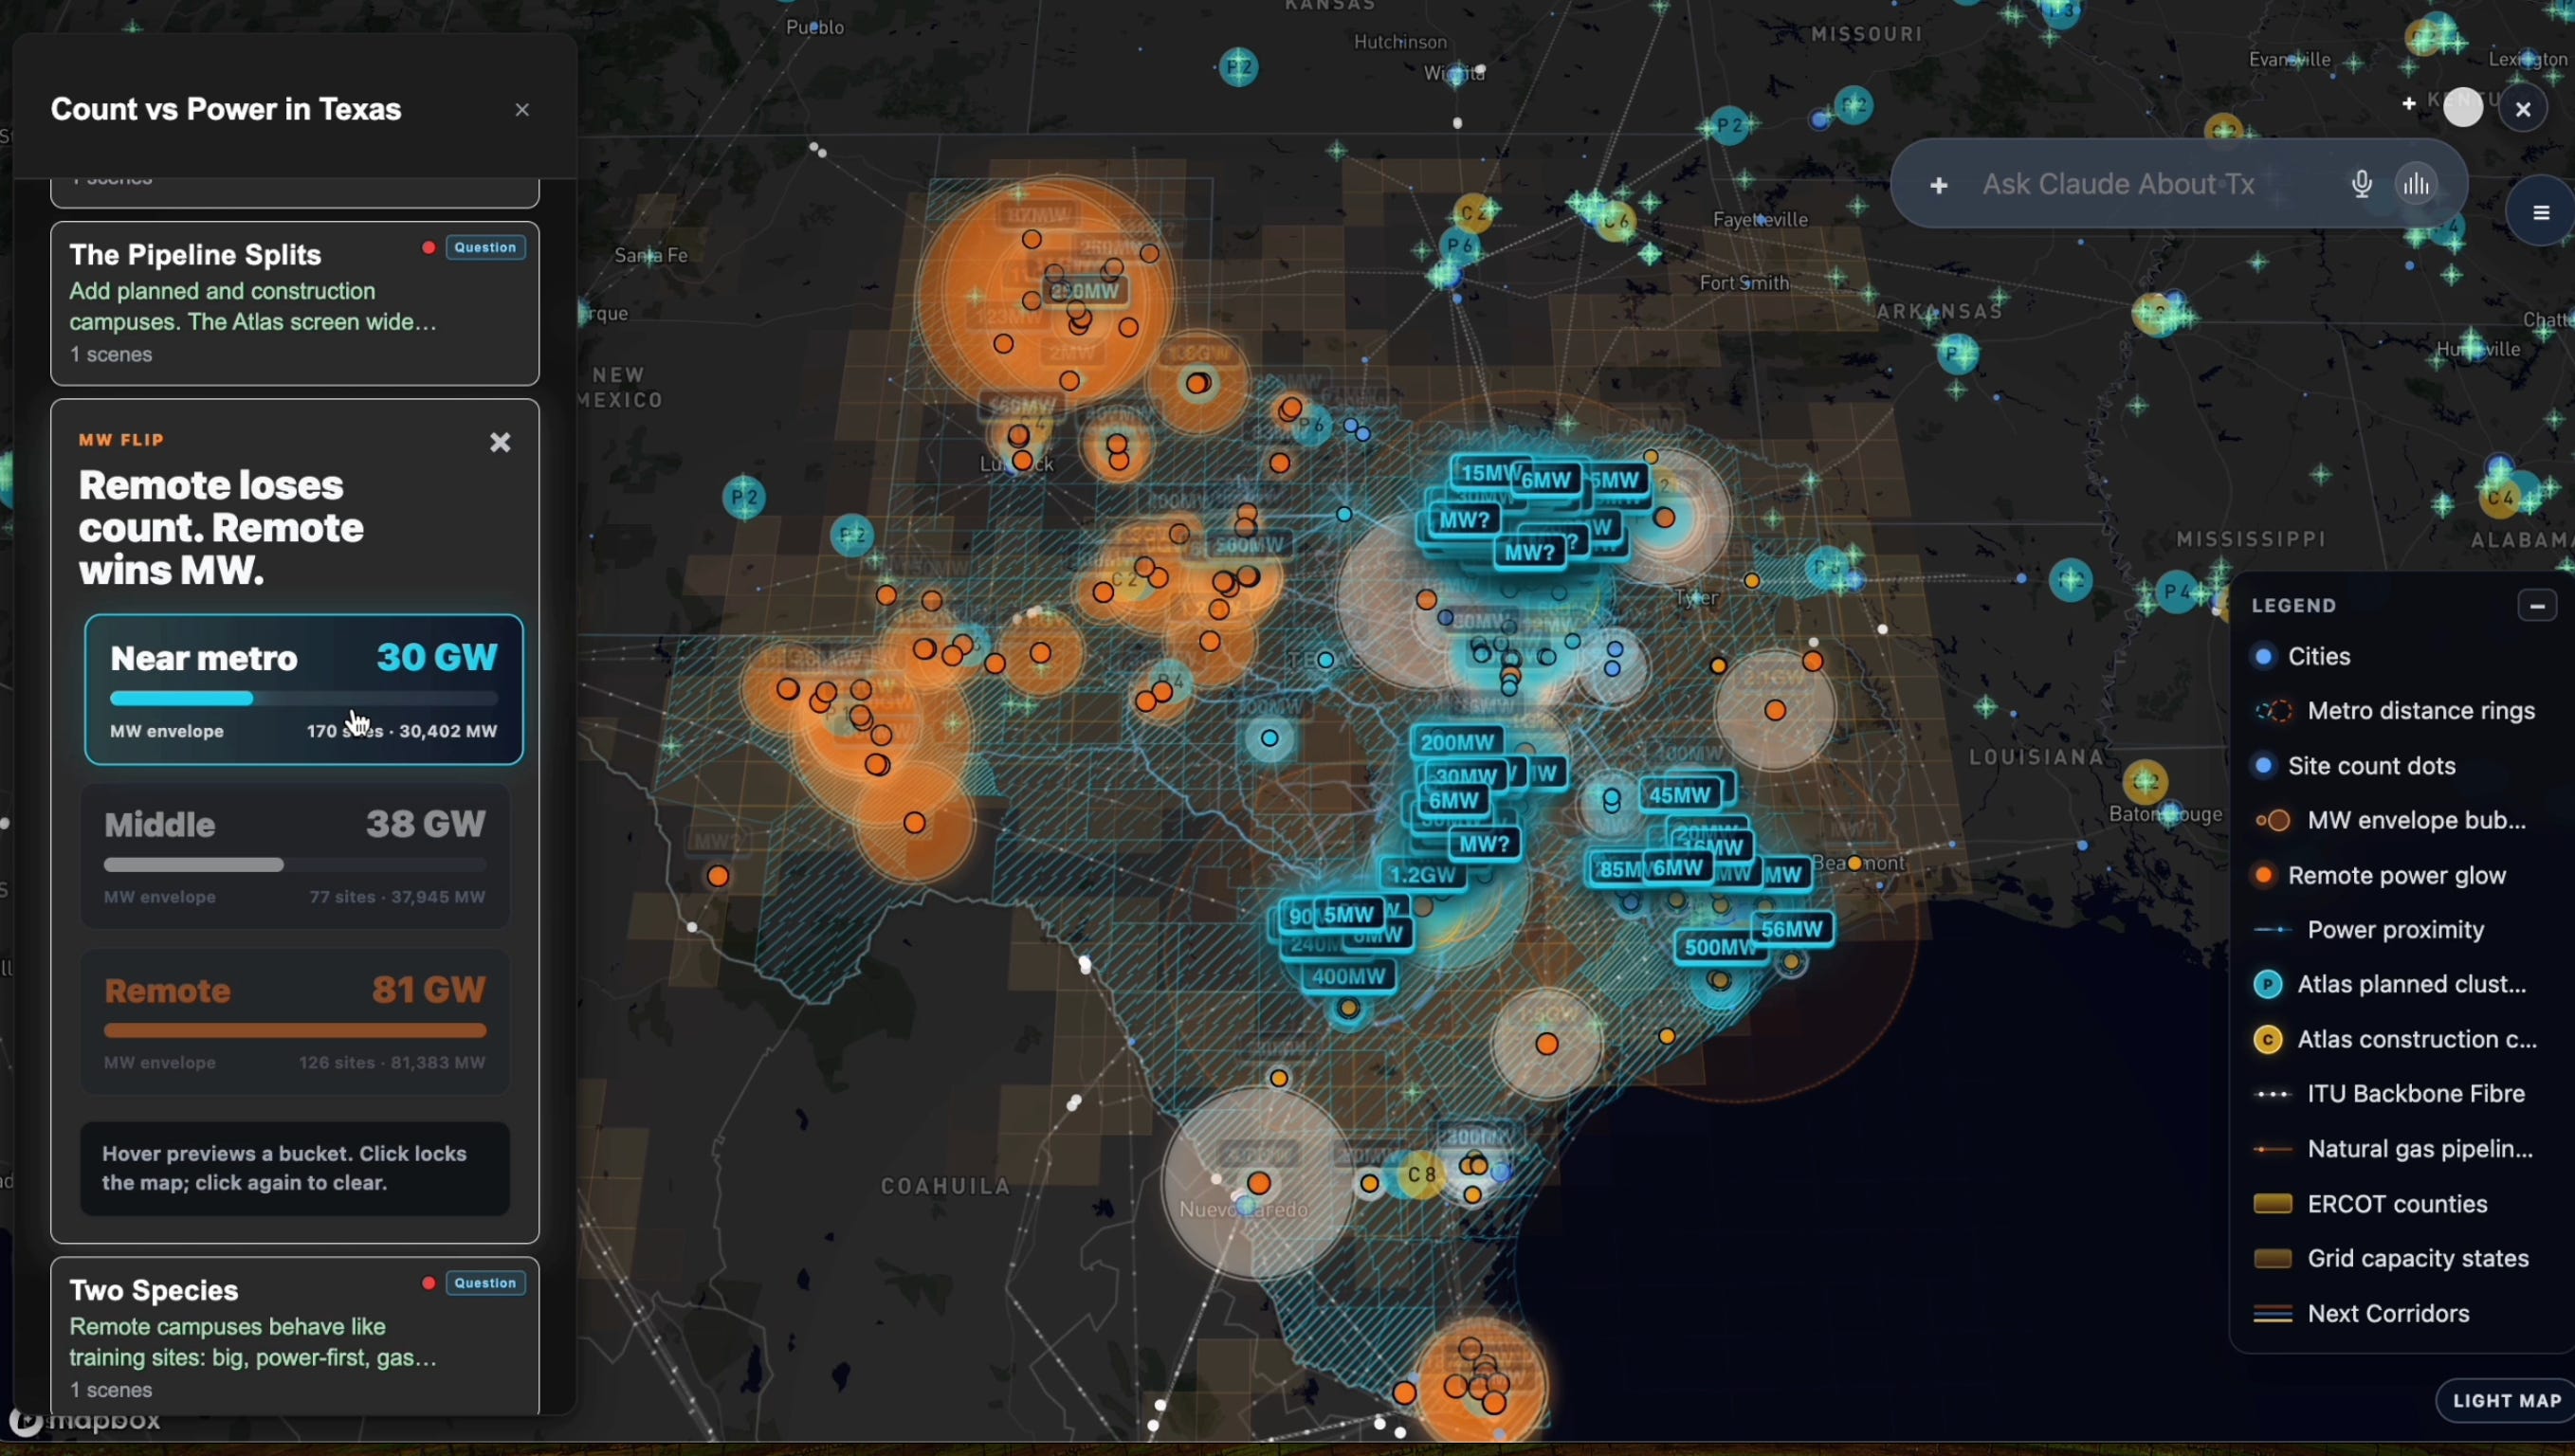
But if you stop counting buildings and start counting megawatts, and you see something very different.
Near the metros: 30,402 MW:
Remote counties: 81,383 MW:
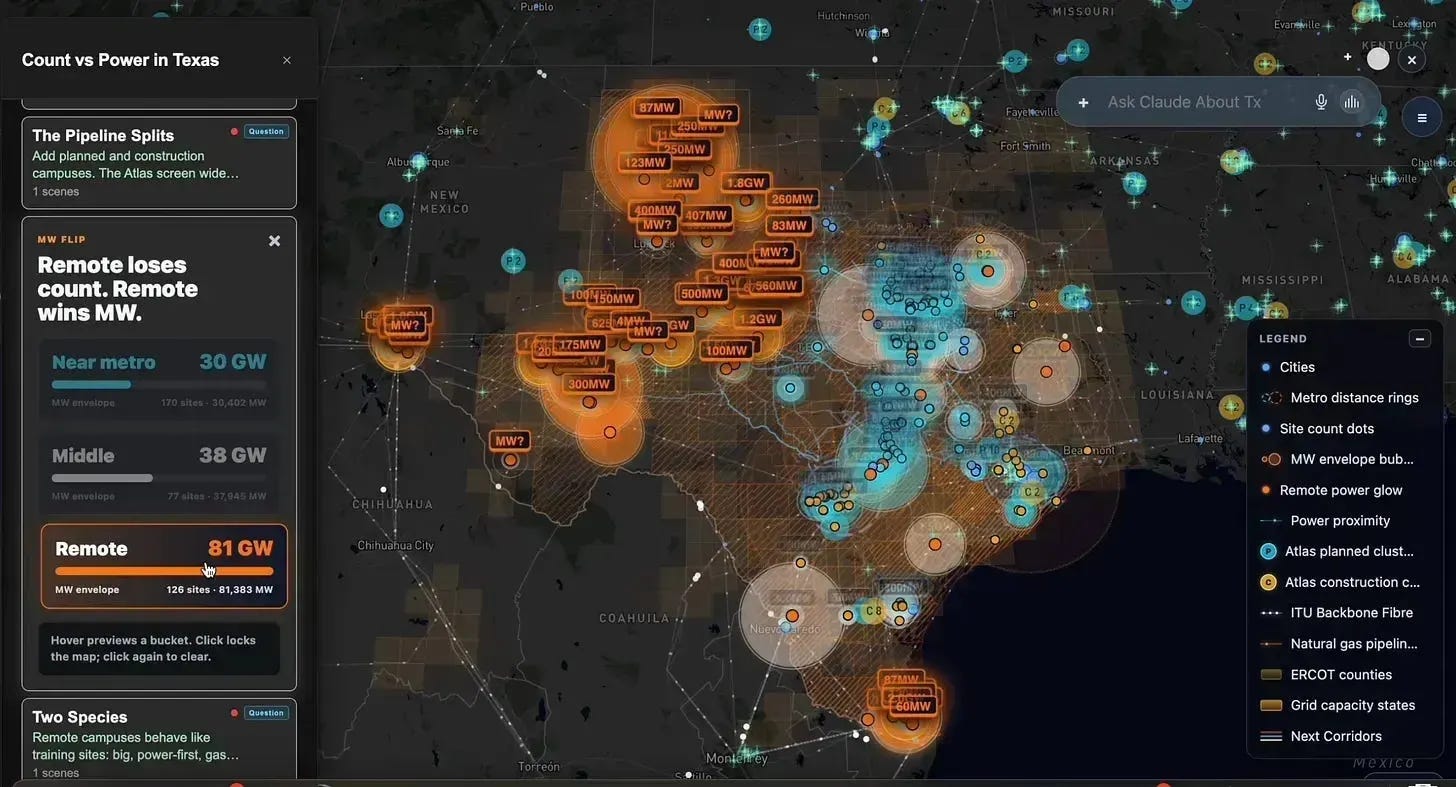
Almost three times the load, in places with very few people around.
So now there are two real maps pointing in opposite directions. The count map says compute is urban. The power map says compute already moved, west and north, out past the cities into counties most Texans would have to look up.
This is worth paying attention to, not because it proves some grand theory, but because it breaks a shortcut people lean on all the time: more sites means more load. That used to be roughly true. It isn’t anymore. The place with the most buildings is no longer the place with the most power, and the gap isn’t small.
What the permits won’t tell you
Permits don’t say what any of these sites will actually run. Training, inference, cloud, colocation, enterprise. None of that is in the filing. That’s just not how permits work.
You could use common sense and say the small sites near cities are for inference and the giant remote loads are for training. Maybe. Probably, even, in a lot of cases. But not always, and a permit will never prove it. So I’m not going to pretend the data says something it doesn’t. What I can say is narrower and, I think, more useful: site count and power capacity are no longer telling the same story about Texas. They’re telling opposite ones.
Why it matters
If you’re buying land, building power, underwriting load, or just trying to read where this market is heading, which map you use changes the answer.
Count buildings and you see a metro play, where being near a city is the thing that matters. Land near the triangle, grid interconnection, competing with warehouses and logistics for the same parcels. Count megawatts and that story falls apart. The load is going where the power is, which is out where almost nobody lives, and the calculus there looks nothing like a metro build. Gas, water, land, transmission, and a relationship with the grid that a downtown developer never has to think about.
Same industry. Same state. Completely different map depending on what you decide to count
Where it’s going
There’s a second split hiding in the numbers, between what’s operating now and what’s planned or under construction. The early read is that the current footprint still leans metro, the sites already running are closer to the cities. But the pipeline, the stuff being planned and built right now, widens the power split rather than closing it.
If that holds, the remote power map isn’t just a snapshot of where things are. It’s the direction. The metro map is the present. The power map is the future, and the future is being poured in counties nobody is looking at.
That’s the next piece, once I’m sure the pipeline read holds up. For now the point is simpler than any theory about training or inference or what the hyperscalers are thinking. Texas hands you two honest maps of the same thing, and they don’t agree. Most people are looking at the one with the buildings. The one with the power is the one that moved.
Reply or comment “method” if you want access to the live Texas map to see where the megawatt figures come from. Part 3, on the pipeline, when the read holds.
method
method